Empowering Startups: Strategies for Success
The startup ecosystem is a complex network of various stakeholders, including entrepreneurs, investors, mentors, and support organizations, all of whom play a crucial role in fostering innovation and economic growth. At its core, the ecosystem is characterized by its dynamic nature, where ideas are rapidly transformed into viable business models. This environment thrives on collaboration and knowledge sharing, which are essential for nurturing new ventures.
Understanding this ecosystem requires an appreciation of the interdependencies among its components, such as incubators, accelerators, venture capital firms, and government policies that can either facilitate or hinder entrepreneurial activities. In many regions, the startup ecosystem is bolstered by a vibrant community of entrepreneurs who share resources and experiences.
For instance, Silicon Valley is often cited as a prime example of a successful startup ecosystem due to its concentration of tech talent, access to venture capital, and a culture that encourages risk-taking. However, emerging ecosystems in cities like Berlin, Tel Aviv, and Bangalore are also gaining recognition for their unique contributions to the global startup landscape. Each ecosystem has its own characteristics shaped by local culture, economic conditions, and available resources, making it essential for entrepreneurs to understand the specific dynamics at play in their region.
Key Takeaways
- Understanding the startup ecosystem is crucial for success, as it involves knowing the market, competition, and potential challenges.
- Building a strong team is essential for a startup’s success, as it requires a diverse set of skills and expertise to navigate the challenges of entrepreneurship.
- Creating a solid business plan is necessary to outline the startup’s goals, target market, financial projections, and marketing strategy.
- Leveraging technology and innovation can give startups a competitive edge and help them stay ahead in the market.
- Securing funding and investment is vital for startups to grow and expand, and it requires a strategic approach and a compelling pitch to attract investors.
Building a Strong Team
The Ideal Team: Diverse and Dynamic
The ideal team is diverse, bringing together different perspectives and expertise that can drive innovation and problem-solving. For example, a tech startup may benefit from having a mix of software developers, marketing specialists, and financial analysts who can collectively address various aspects of the business. This diversity fosters creativity and enhances the team’s ability to adapt to challenges as they arise.
Effective Communication and Collaboration
Moreover, effective communication and collaboration are vital components of a strong team. Establishing a culture of openness encourages team members to voice their ideas and concerns without fear of judgment. Regular team meetings, brainstorming sessions, and feedback loops can help maintain alignment and ensure that everyone is working towards the same goals.
A Supportive Environment for Success
A strong team not only enhances productivity but also creates a supportive environment where individuals feel valued and motivated to contribute their best efforts. Investing in team-building activities can strengthen relationships among members, fostering trust and camaraderie.
Creating a Solid Business Plan
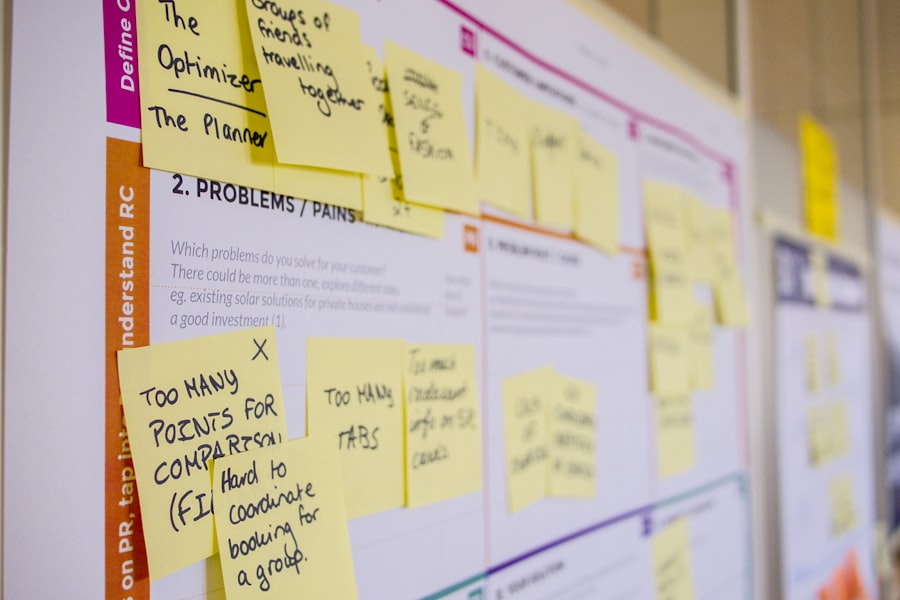
A well-structured business plan serves as a roadmap for any startup, outlining its vision, objectives, target market, competitive landscape, and financial projections. This document is not merely a formality; it is an essential tool for guiding decision-making and measuring progress over time. A comprehensive business plan should begin with an executive summary that succinctly captures the essence of the business idea.
Following this, detailed sections should delve into market analysis, identifying customer segments and assessing market demand. For instance, a startup focused on sustainable fashion would need to analyze consumer trends towards eco-friendly products and identify key demographics that prioritize sustainability. Financial projections are another critical component of the business plan.
Startups must provide realistic estimates of revenue streams, expenses, and cash flow over the next few years. This financial foresight not only helps in managing resources effectively but also serves as a persuasive tool when seeking investment. Investors often scrutinize these projections to gauge the viability of the business model.
Additionally, outlining potential risks and mitigation strategies demonstrates foresight and preparedness, which can instill confidence in stakeholders. A solid business plan is not static; it should evolve as the startup grows and adapts to changing market conditions.
Leveraging Technology and Innovation
| Metrics | Data |
|---|---|
| Number of new technology implementations | 15 |
| Percentage increase in productivity due to technology | 20% |
| Number of innovative ideas generated | 50 |
| Percentage of employees trained in new technologies | 80% |
In today’s fast-paced business environment, leveraging technology is paramount for startups aiming to gain a competitive edge. The integration of innovative tools can streamline operations, enhance customer experiences, and drive growth. For instance, cloud computing allows startups to access scalable resources without significant upfront investments in infrastructure.
This flexibility enables them to focus on core business activities while minimizing operational costs. Furthermore, utilizing data analytics can provide valuable insights into customer behavior and preferences, allowing startups to tailor their offerings more effectively. Innovation extends beyond technology; it encompasses creative problem-solving and the ability to pivot in response to market demands.
For example, companies like Airbnb began with a simple concept but continuously evolved their platform based on user feedback and market trends. This adaptability not only helps in refining products but also positions startups as leaders in their respective industries.
By embracing both technological advancements and innovative thinking, startups can navigate challenges more effectively and seize new opportunities as they arise.
Securing Funding and Investment
Securing funding is often one of the most daunting challenges faced by startups. Entrepreneurs must explore various avenues for financing their ventures, including bootstrapping, angel investors, venture capitalists, crowdfunding platforms, and government grants. Each funding source comes with its own set of advantages and considerations.
For instance, bootstrapping allows founders to maintain full control over their business but may limit growth potential due to constrained resources. On the other hand, venture capital can provide substantial funding but often requires giving up equity and adhering to specific performance metrics. Crafting a compelling pitch is crucial when seeking investment.
Entrepreneurs must articulate their value proposition clearly while demonstrating market potential and scalability. A well-prepared pitch deck should include key metrics such as customer acquisition costs, lifetime value of customers, and projected growth rates. Additionally, building relationships with potential investors through networking events or industry conferences can enhance credibility and increase the likelihood of securing funding.
Ultimately, understanding the nuances of different funding options enables startups to make informed decisions that align with their long-term goals.
Establishing a Strong Brand and Marketing Strategy

Building a Compelling Brand Narrative
For example, companies like Patagonia have successfully built their brand around environmental sustainability, appealing to consumers who prioritize ethical consumption. This approach not only attracts customers but also creates a sense of purpose and belonging among them.
Effective Marketing Strategies for Startups
An effective marketing strategy is equally important for driving awareness and attracting customers. Startups should leverage digital marketing techniques such as social media advertising, content marketing, and search engine optimization (SEO) to reach their audience effectively. By utilizing these channels, startups can increase their online visibility and reach a wider audience.
Measuring and Optimizing Marketing Performance
Engaging content that educates or entertains can help establish authority in the industry while fostering community engagement. Additionally, utilizing analytics tools allows startups to track campaign performance and make data-driven adjustments to optimize results continually. By combining a strong brand identity with targeted marketing efforts, startups can create lasting impressions that translate into customer loyalty.
Creating Lasting Impressions through Branding and Marketing
Navigating Legal and Regulatory Challenges
The legal landscape presents numerous challenges for startups that must be navigated carefully to avoid potential pitfalls. Entrepreneurs need to understand the regulatory requirements specific to their industry, including licensing, permits, intellectual property rights, and employment laws. For instance, tech startups may face stringent data protection regulations such as GDPR in Europe or CCPA in California that dictate how they handle user data.
Failing to comply with these regulations can result in hefty fines or legal repercussions that could jeopardize the business. Engaging legal counsel early in the startup process can provide invaluable guidance on these matters. A knowledgeable attorney can help draft contracts, protect intellectual property through patents or trademarks, and ensure compliance with relevant laws.
Additionally, staying informed about changes in legislation is crucial for adapting business practices accordingly. Startups should also consider establishing internal policies that promote ethical practices and transparency within their operations. By proactively addressing legal challenges, startups can mitigate risks and focus on growth without being hindered by unforeseen legal issues.
Scaling and Sustaining Growth
Once a startup has established itself in the market, scaling becomes the next significant challenge. Growth requires careful planning and execution to ensure that operations can handle increased demand without compromising quality or customer satisfaction. Startups must assess their infrastructure—this includes technology systems, supply chain logistics, and human resources—to determine whether they are equipped for expansion.
For example, a food delivery startup may need to invest in additional delivery personnel or optimize its logistics software to manage increased order volumes effectively. Sustaining growth also involves continuous innovation and adaptation to changing market conditions. Startups should regularly solicit feedback from customers to identify areas for improvement or new opportunities for product development.
Additionally, exploring new markets or diversifying product offerings can help mitigate risks associated with reliance on a single revenue stream. Companies like Slack have successfully scaled by expanding their platform’s capabilities while maintaining a focus on user experience. By fostering a culture of agility and responsiveness within the organization, startups can navigate the complexities of scaling while ensuring long-term sustainability in an ever-evolving business landscape.
If you’re interested in learning more about startups and how they can thrive in today’s competitive market, be sure to check out this article on JustStartup. This website offers valuable insights and resources for entrepreneurs looking to launch their own businesses and achieve success. Whether you’re a seasoned entrepreneur or just starting out, JustStartup has the tools and information you need to take your startup to the next level.
FAQs
What is a startup?
A startup is a newly established business, typically small in size, that is founded by one or more entrepreneurs to develop a unique product or service and bring it to market.
What makes a company a startup?
A company is considered a startup when it is in the early stages of its development, focused on developing and validating a scalable business model, and typically operating with limited resources and a high degree of uncertainty.
What are some common characteristics of startups?
Common characteristics of startups include a focus on innovation, agility, risk-taking, and a strong entrepreneurial spirit. Startups often operate in dynamic and rapidly changing environments.
How do startups typically fund their operations?
Startups often rely on various sources of funding, including personal savings, loans, angel investors, venture capital, crowdfunding, and government grants. They may also generate revenue through early sales or partnerships.
What are some challenges that startups commonly face?
Startups commonly face challenges such as securing funding, building a customer base, developing a viable business model, navigating regulatory requirements, and competing with established companies in the market.
What are some examples of successful startups?
Some well-known successful startups include Airbnb, Uber, Spotify, Dropbox, and Slack. These companies have achieved significant growth and success by disrupting traditional industries and meeting the needs of modern consumers.